Form 990 Preparation Checklist: What You Need Before Filing
Key Takeaways
Gather your basic organizational details first. Have your EIN, legal name, tax year dates, and IRS determination letter, if applicable, ready before preparing your Form 990.
Organized financial records are the most time-consuming part of preparation. Keep revenue, expense, and balance sheet data separated and categorized throughout the year.
Form 990 includes detailed governance questions. Knowing your board composition and which governance policies your nonprofit has in place can make filing easier.
The version of Form 990 your nonprofit files depends on your gross receipts and total assets. Confirm the correct form before you begin.
Failing to file required annual IRS returns or notices for three consecutive tax years generally results in automatic revocation of federal tax-exempt status. Filing on time or requesting an available extension helps your organization stay on track.
Filing Form 990 is easier when your records are in order before you start. This checklist walks nonprofit founders through the financial and governance information they need to gather ahead of their annual IRS filing.
Filing your Form 990 does not have to be stressful. For most nonprofits, the hardest part is not the form itself. It is finding the right information when you need it. When your financial records and governance documents are organized ahead of time, the filing process goes much more smoothly.
This checklist is designed to help nonprofit founders and administrators know exactly what to gather before sitting down to complete their annual IRS filing. Whether you are filing for the first time or just want a more organized process this year, having the right information ready makes a real difference.
Staying on top of annual reporting is one of the most important parts of nonprofit compliance. The good news is that preparation is something you can start well before your deadline.
What Is Form 990 and Why Does Preparation Matter?
Quick Answer
Form 990 is an annual information return that many tax-exempt nonprofits file with the IRS. Smaller organizations may qualify to file Form 990-EZ or Form 990-N instead, while some organizations are exempt from filing. Preparing in advance means gathering financial statements, program descriptions, board information, and other required details. This helps your nonprofit file accurately and on time.
Which Version of Form 990 Does Your Nonprofit File?
Not all nonprofits file the same form. The version your organization uses depends on your annual gross receipts and total assets.
| Form | Who Files It |
|---|---|
| Form 990-N (e-Postcard) | Gross receipts normally $50,000 or less |
| Form 990-EZ | Gross receipts less than $200,000 and total assets less than $500,000 |
| Form 990 (Full) | Gross receipts $200,000 or more, or total assets $500,000 or more |
Private foundations file Form 990-PF regardless of size.
These thresholds apply to organizations eligible to use each form. Some organizations, including private foundations and certain other tax-exempt entities, follow different filing requirements. Organizations eligible for Form 990-N may also choose to file a more detailed return.
For a full breakdown of eligibility rules and filing thresholds, see When Your Nonprofit Must File 990-N, 990-EZ, or 990 and Understanding IRS Form 990 Filing Requirements.
The steps below focus on preparing the information needed to file Form 990 or Form 990-EZ. If your nonprofit qualifies for Form 990-N, you'll generally need much less information to complete your annual filing.
Ready to Stay on Track With Nonprofit Compliance?
Need to file your annual Form 990-N? Beacon Nonprofit can help you complete your filing and stay on track with your nonprofit's annual reporting responsibilities.
File Your Form 990-NStep 1: Gather Your Basic Organizational Information
Start with the foundational details about your organization. These are the facts that identify your nonprofit to the IRS.
- Legal name of the organization, exactly as it appears in your IRS determination letter
- Employer Identification Number (EIN)
- Mailing address and principal office address
- Tax year start and end dates
- Name and contact information for a principal officer
- Organization's website address, if applicable
- Confirmation of your tax-exempt status and the section under which you are exempt (most commonly 501(c)(3))
- Any name changes or address changes during the year
Having your IRS determination letter on hand is helpful. It confirms your EIN, exemption status, and the effective date of your tax-exempt recognition.
Step 2: Collect Your Financial Records
This is usually where preparation takes the most time. The IRS requires a complete picture of your nonprofit's finances for the year. Accurate, well-organized nonprofit financial statements make this step much easier.
Revenue
- Total contributions, gifts, and grants received
- Program service revenue (fees charged for services)
- Investment income
- Gross fundraising event revenue and associated direct expenses, tracked separately
- Other income sources
Expenses
- Total functional expenses, broken down by program services, management and general, and fundraising
- Grants and similar amounts paid to others
- Salaries, compensation, and employee benefits
- Professional fees and other payments to independent contractors
- Occupancy, travel, and other operating expenses
Balance Sheet Items
- Cash and savings balances at the beginning and end of the year
- Accounts receivable and payable
- Land, buildings, and equipment (net of depreciation)
- Total assets and total liabilities
- Net assets or fund balances, including amounts with donor restrictions and without donor restrictions, as applicable.
If your nonprofit does not already have organized books, reviewing nonprofit bookkeeping basics before you begin will help you understand how to structure your records.
Step 3: Compile Governance and Program Information
Form 990 asks detailed questions about how your nonprofit is governed and what programs it runs. This section is important for transparency and public accountability.
Governance
- Current list of board members, trustees, and officers, including names, titles, and hours worked per week.
- Whether any board members are related to each other or to key employees.
- Written policies your organization has in place, including conflict of interest, whistleblower, and document retention policies.
- Check which policies your organization actually maintains. Form 990 asks about certain governance policies, but not every policy listed is universally required by federal law.
- Whether a complete copy of Form 990 was provided to voting board members before filing, and how the return was reviewed, if applicable.
- Any significant changes to your organizing documents during the year.
Understanding board member fiduciary duties can help you answer governance questions with confidence and demonstrate that your organization is well-managed.
Strong governance is also one of the foundations covered in Nonprofit Management 101, which offers practical guidance on building a sustainable organization.
Program Service Accomplishments
- Description of your three largest program services by expense
- Number of people served, if applicable
- Grants or allocations made as part of program activities
- Whether any programs were started, changed, or discontinued during the year
Step 4: Prepare Compensation and Employee Information
If your nonprofit has paid staff or compensates key individuals, you will need to gather specific information about compensation.
- Names and titles of all current officers, directors, trustees, and key employees
- Reportable compensation paid through your organization's W-2
- Compensation from related organizations, if applicable
- Benefits and deferred compensation
- Identify up to five current highest compensated employees, other than officers, directors, trustees, or key employees, whose reportable compensation from the organization and related organizations exceeded $100,000. Also review the IRS reporting rules for former officers, directors, trustees, and key employees.
- Identify the five highest compensated independent contractors paid more than $100,000 for services, if applicable.
The IRS defines key employees and highly compensated individuals specifically in the Form 990 instructions. Reviewing the IRS Form 990 instructions directly will help you identify who needs to be reported and how.
Step 5: Review Schedules You May Need to Complete
Depending on your organization's activities, you may need to complete one or more schedules attached to Form 990. Common schedules include:
- Schedule A — Public Charity Status and Public Support. Required for 501(c)(3) organizations filing Form 990 and certain other organizations treated as 501(c)(3) for this purpose.
- Schedule B — Schedule of Contributors. Required when contributions meet applicable IRS reporting thresholds. Contributor names and addresses are generally excluded from public disclosure for most Form 990 filers, but exceptions apply.
- Schedule D — Supplemental Financial Statements. Required when applicable reporting conditions are met, such as certain donor-advised funds, endowments, escrow arrangements, or other financial items identified in Form 990 Part IV.
- Schedule G — Reports fundraising activities and gaming, if applicable
- Schedule L — Transactions with interested persons, such as loans to officers or board members
- Schedule O — Supplemental information; used for required explanations throughout the form
The IRS provides a full list of schedules and when each is required in the Form 990 instructions. If you are unsure which schedules apply, working with a qualified preparer can help. You can also explore nonprofit tax services to compare filing support options.
What to Gather for Schedule D
Your nonprofit's answers in Form 990 Part IV generally determine which parts of Schedule D it must complete, subject to applicable exceptions or optional reporting provisions. Not every nonprofit will need Schedule D, and not every organization that files it will complete every section.
If the relevant Schedule D section applies to your organization, gather the records you need before you begin. The IRS Instructions for Schedule D explain which conditions trigger each part and what information is required. Examples of records you may need include:
- Endowments — Beginning and ending balances, contributions, investment earnings, grants or scholarships paid out, and administrative expenses for applicable endowment funds, along with board-designated endowment details if applicable
- Escrow or custodial accounts — Documentation identifying the account, the custodian or agent, purpose, beginning and ending balances, and any additions or distributions during the year
- Financial statement supporting schedules — Itemized schedules for amounts reported on the balance sheet or statement of activities that Form 990 requires to be broken out in Schedule D, such as investments, land and buildings, or other assets and liabilities
Getting Ready to File
Once you have gathered everything on this checklist, you are in a strong position to complete your Form 990 accurately and on time. The IRS deadline for Form 990 is the 15th day of the 5th month after your fiscal year ends. For nonprofits on a calendar year, that is May 15. Extensions are available using Form 8868, which gives you an automatic 6-month extension.
Form 990 must generally be filed electronically through an IRS-authorized e-file provider. Check the applicable IRS filing instructions and choose your filing method before the deadline.
Filing accurately and on time protects your tax-exempt status. Nonprofits that fail to file for three consecutive years automatically lose their exemption under IRS automatic revocation rules.
If your organization is still early in its journey, understanding how to form a nonprofit in 8 steps can help you build the kind of organized foundation that makes annual reporting easier every year.
Frequently Asked Questions
The deadline is the 15th day of the fifth month after your fiscal year ends. For nonprofits operating on a calendar year (January 1 to December 31), that is May 15. You can request an automatic six-month extension for Form 990, Form 990-EZ, or Form 990-PF using IRS Form 8868. Form 990-N cannot be extended.
If your nonprofit files Form 990 late without reasonable cause, the IRS may assess daily penalties. Under the 2025 tax-year instructions, the penalty for smaller organizations is $25 per day, up to the lesser of $13,000 or 5% of annual gross receipts. Larger organizations face higher penalties. Failing to file required annual returns or notices for three consecutive tax years generally results in automatic revocation of federal tax-exempt status.
Not necessarily. Many smaller nonprofits can file Form 990-N or Form 990-EZ without an accountant. Some choose to work with services like Beacon Nonprofit for help completing their Form 990-N filing. The full Form 990 is more complex, and many organizations work with an accountant or tax preparer familiar with nonprofit reporting. The right choice depends on your organization's size, complexity, and internal capacity.
You'll need financial information covering your organization's revenue, expenses, assets, liabilities, and net assets for the reporting year. A statement of financial position, statement of activities, and functional expense records can help you prepare the required Form 990 sections. Reconcile these records with your bookkeeping before filing. Additional financial reporting requirements may apply depending on your organization.
Yes. Form 990 generally must be filed electronically through an IRS-authorized e-file provider. Form 990-EZ also requires electronic filing, and eligible organizations file Form 990-N electronically through the IRS's e-Postcard system.
Related Articles
Nonprofit Compliance Checklist: What Every Founder Needs to Know
Stay organized with this nonprofit compliance checklist covering annual IRS filings, state requirements, board responsibilities, recordkeeping, and key deadlines.
When Your Nonprofit Must File 990-N, 990-EZ, or 990
Not every nonprofit files the same tax return, and knowing which Form 990 your organization is required to submit can save you from costly mistakes. This guide breaks down the differences between 990-N, 990-EZ, and the full Form 990, so you always know where your nonprofit stands.
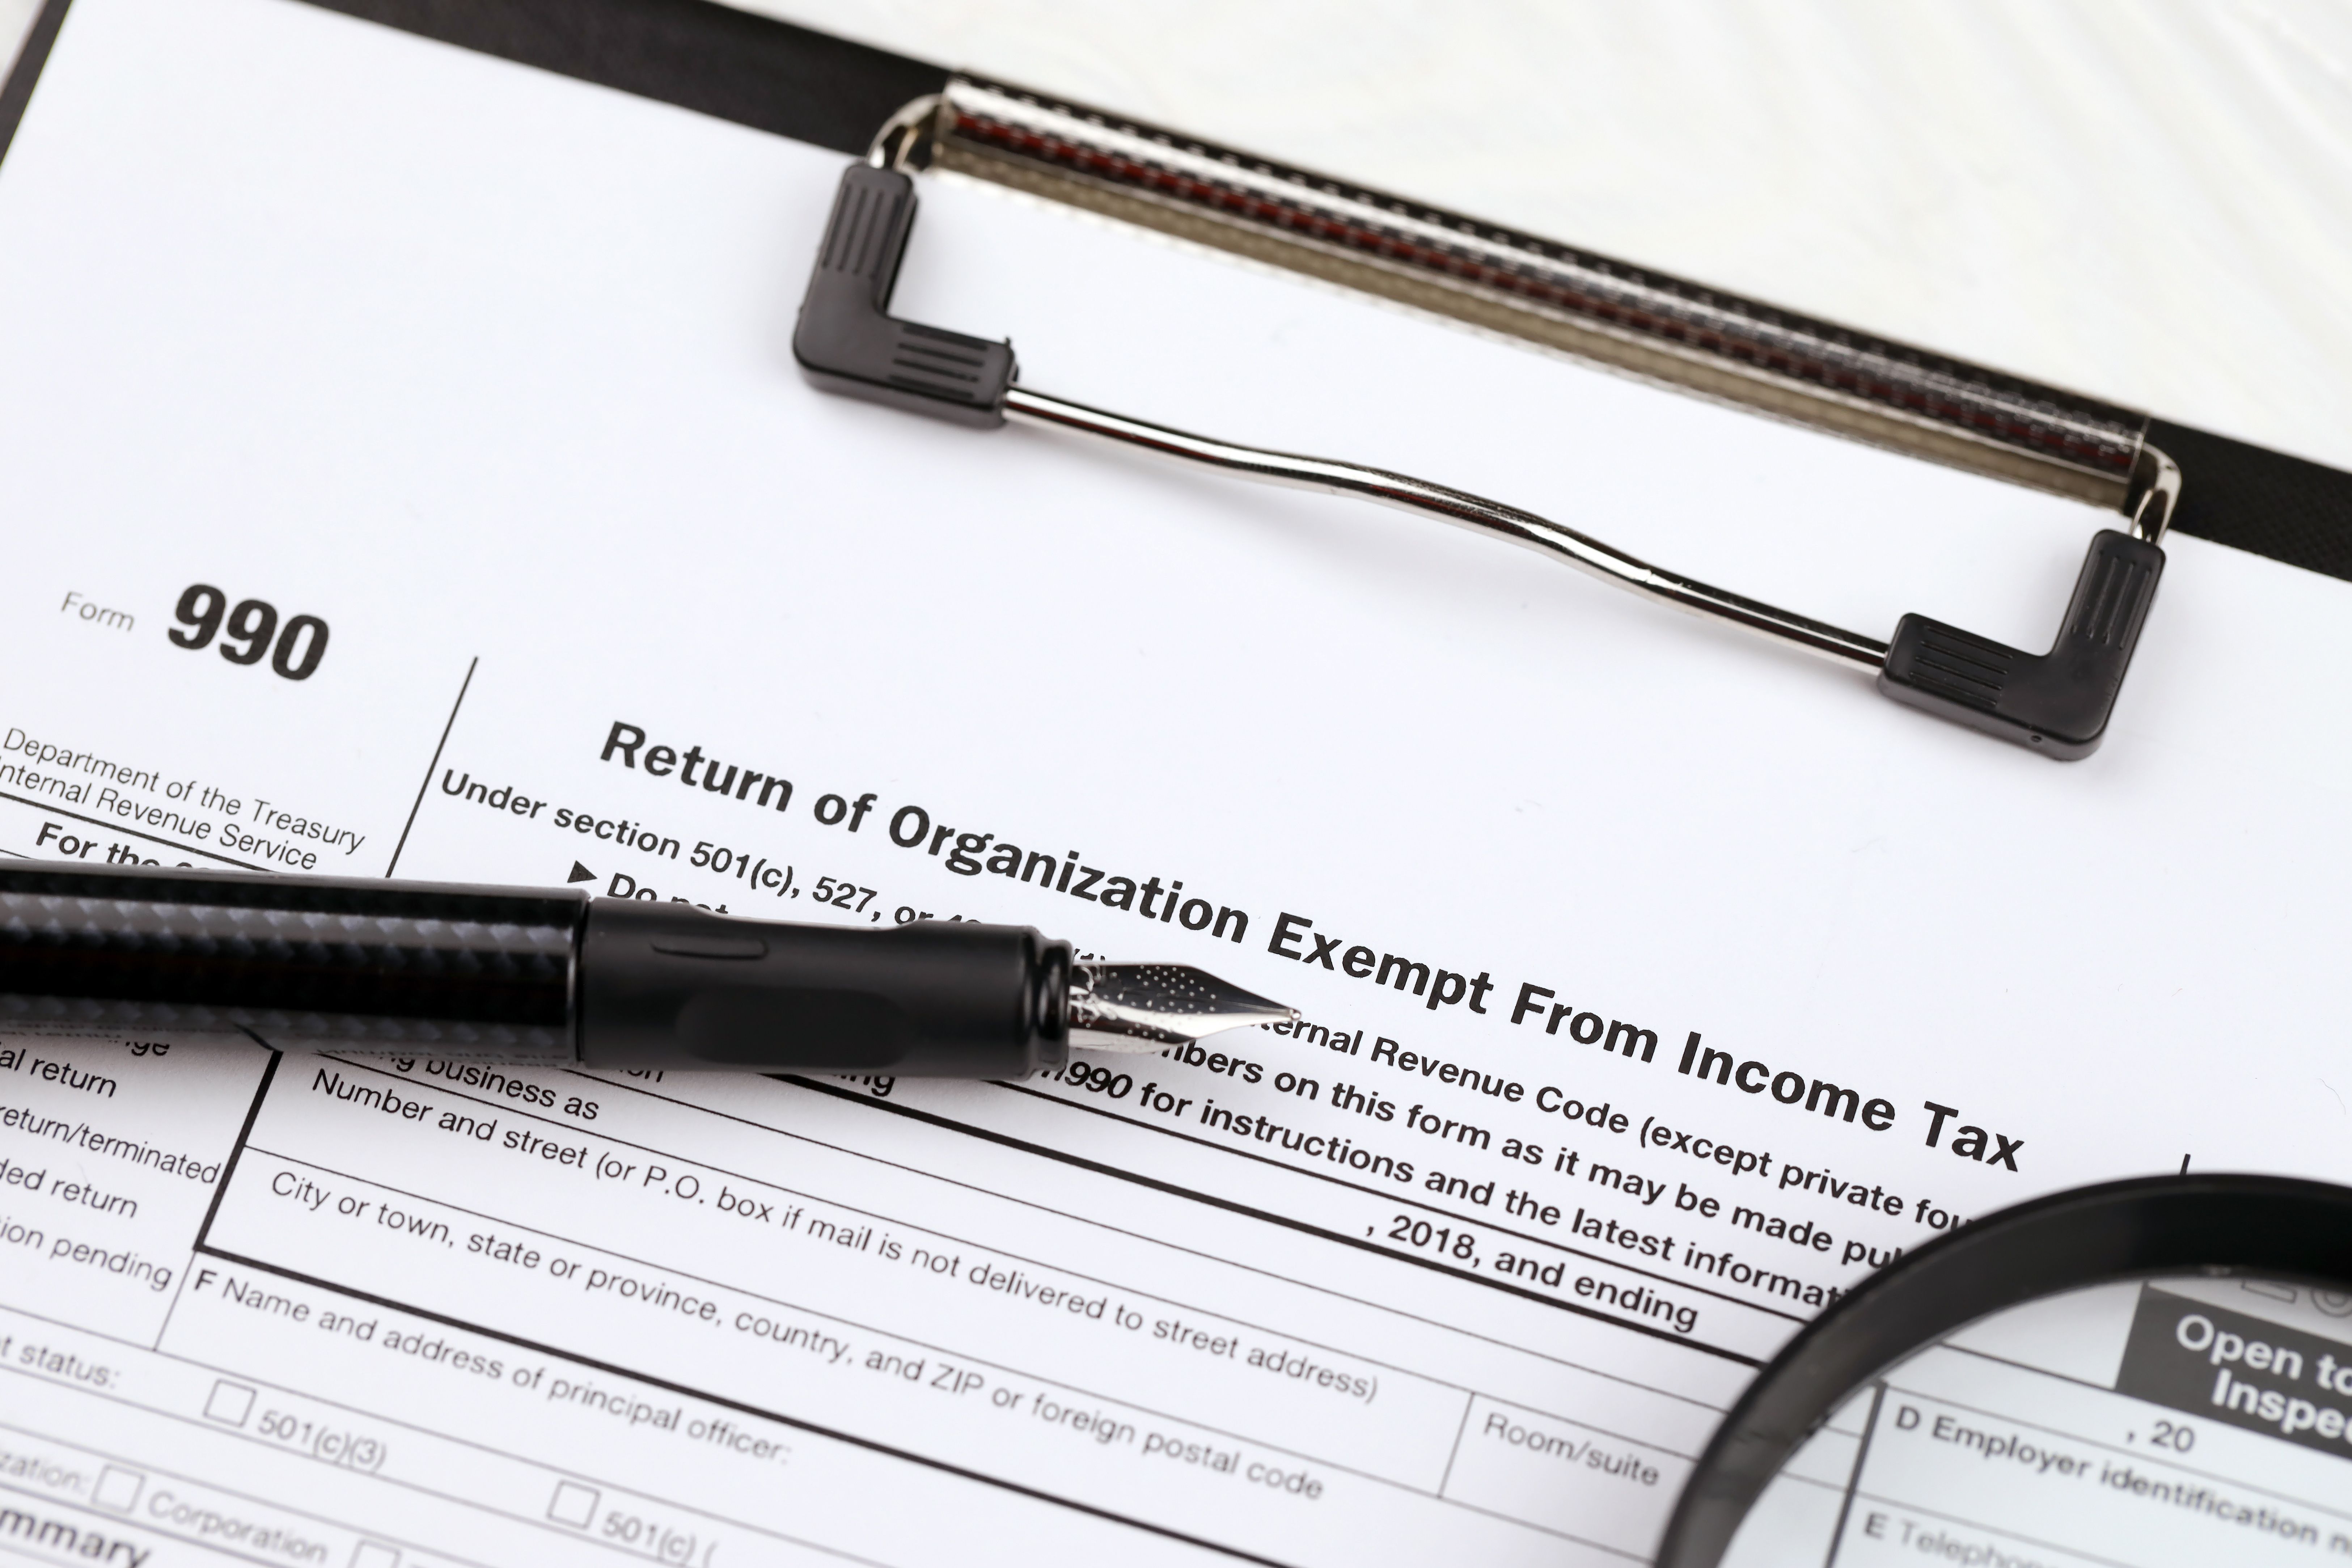
Understanding IRS Form 990 Filing Requirements: 990-N, 990-EZ, and 990 Explained
Nonprofits recognized as tax-exempt organizations typically submit an annual information return to the IRS. Understanding which Form 990 version to file and when to file it helps organizations stay compliant and focused on their mission.
Nonprofit Financial Statements Explained
Nonprofit financial statements are the official records that show how your organization earns and spends money. This guide explains the four core statements every nonprofit should know, how to read them, and why they matter for compliance, donors, and long-term health.
Nonprofit Bookkeeping Basics for New Organizations
Nonprofit bookkeeping means recording every transaction, tracking income and expenses, and reconciling your accounts regularly. This guide covers the day-to-day habits every new nonprofit founder needs to keep their books organized and IRS-ready.
Nonprofit Board Member Fiduciary Duties Explained
Fiduciary duties define what nonprofit board members are legally and ethically required to do. This guide explains the three core duties (care, loyalty, and obedience) in plain language, with practical examples to help first-time founders build a board that leads with integrity.
Nonprofit Management 101: Building a Strong and Sustainable Organization
Learn nonprofit management basics, including board governance, financial oversight, volunteer coordination, and compliance responsibilities that support long-term sustainability.
Nonprofit Tax Services: Comparing Filing Support, Tax Preparation, and Tax Advice
Not sure what nonprofit tax services your organization actually needs? This guide explains the difference between filing support, tax preparation, and tax advice so you can choose the right level of help for your nonprofit.
How to Form a Nonprofit Organization in 8 Steps
Learn how to start a nonprofit organization in eight steps, from state incorporation and board setup to applying for 501(c)(3) tax-exempt status.
Get Nonprofit Tips and Compliance Guidance
Subscribe for updates, insights, and resources that help you stay compliant and grow your mission.